Hail · wind · storm damage
Roof insurance claims, without the runaround.
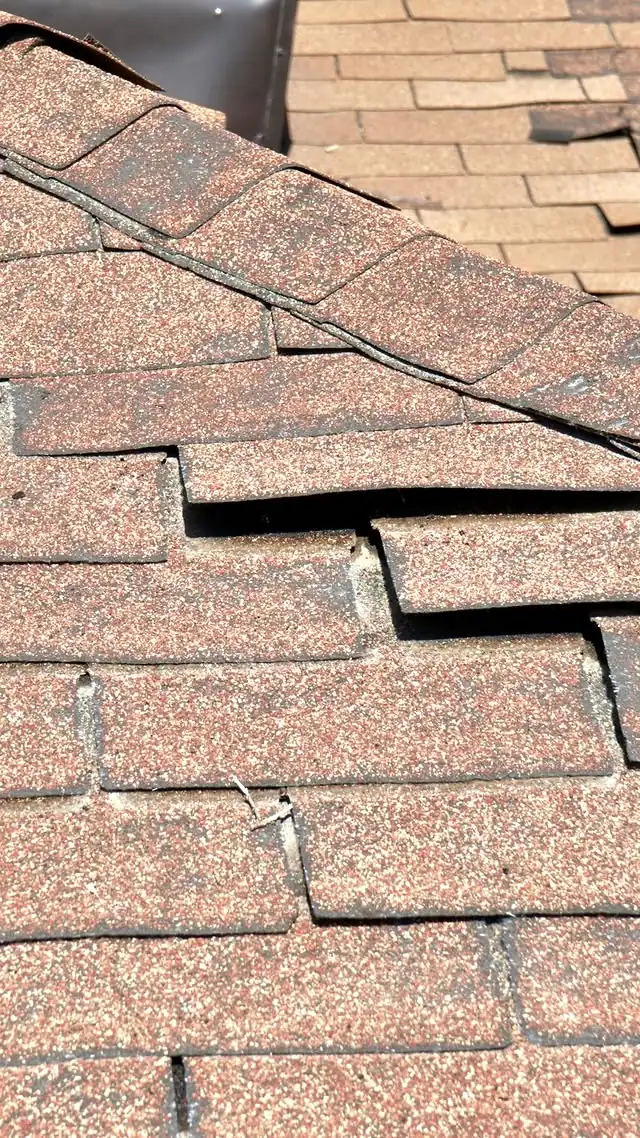
We inspect the roof for free, document every bit of storm damage with photos, give you a straight estimate, and stand on the roof with your adjuster. You stay in charge of your claim; we make sure nothing gets missed.
The six steps
What happens, in order.
Step 01 of 06
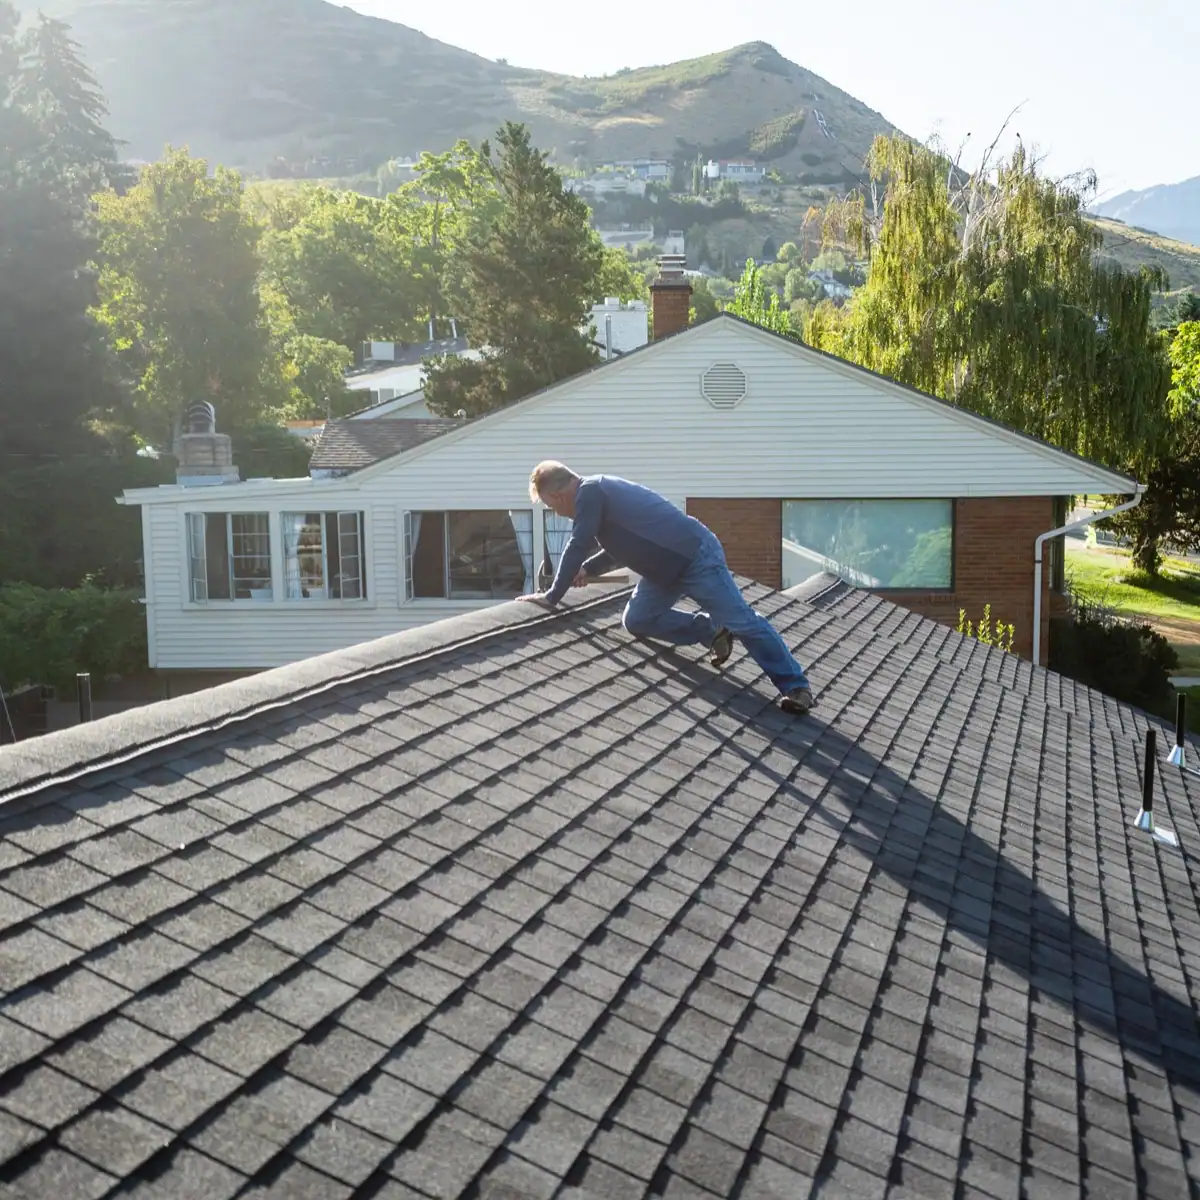
Free inspection
We get on the roof — not just look from the driveway — and photograph every hit, lifted tab and cracked boot.
Step 02 of 06
A damage report you can file
You get a photo report and a straight estimate — we inspect and advise, with no obligation.
Step 03 of 06
You open the claim
File with your insurer using our report. We answer your questions about the process along the way.
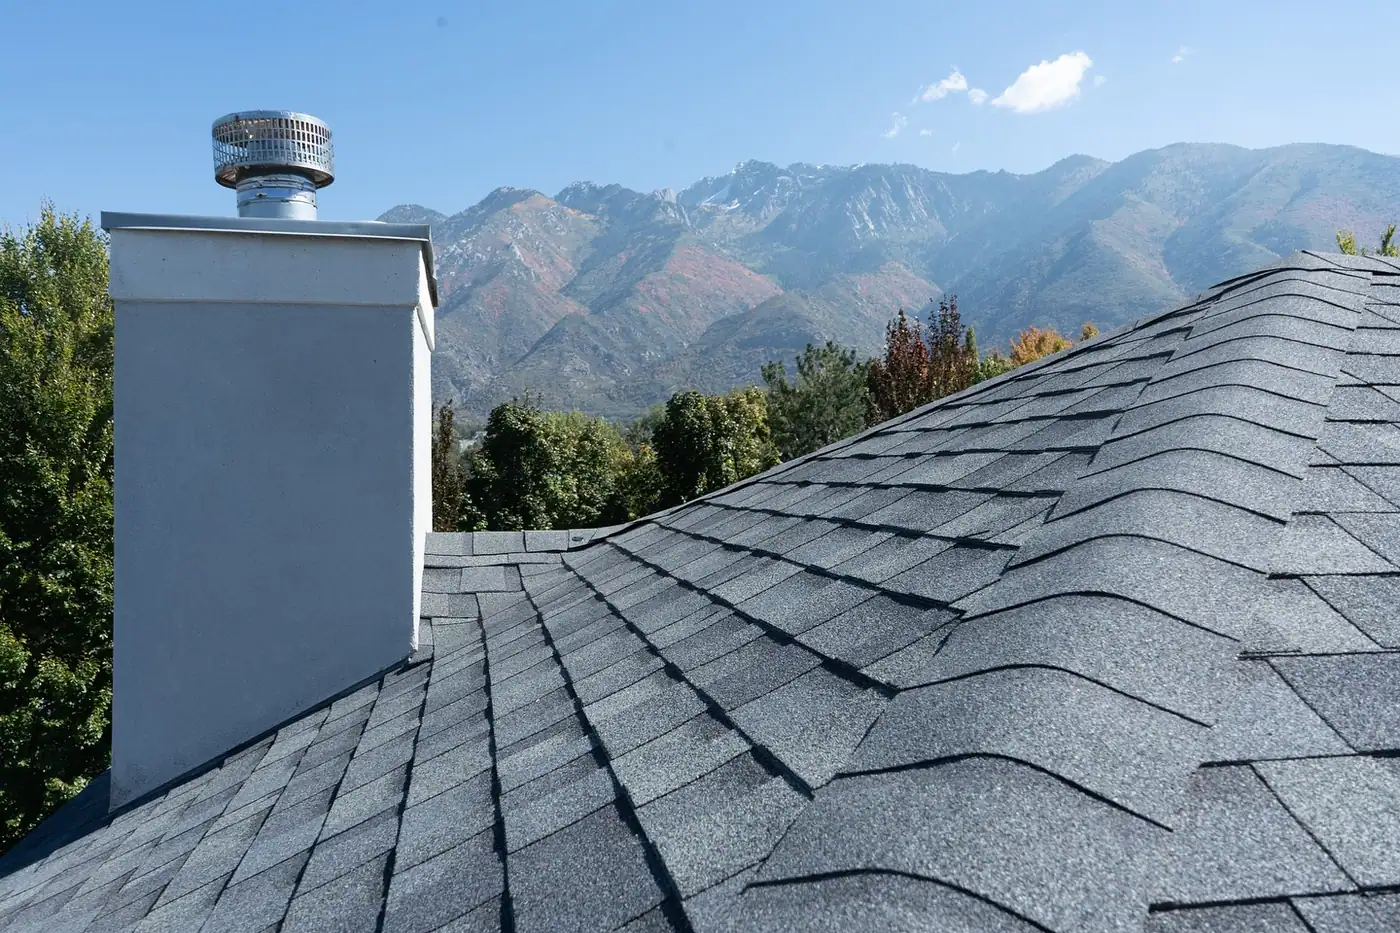
Step 04 of 06
We meet your adjuster
We're on the roof when the adjuster comes, so the damage we documented gets seen — not missed.
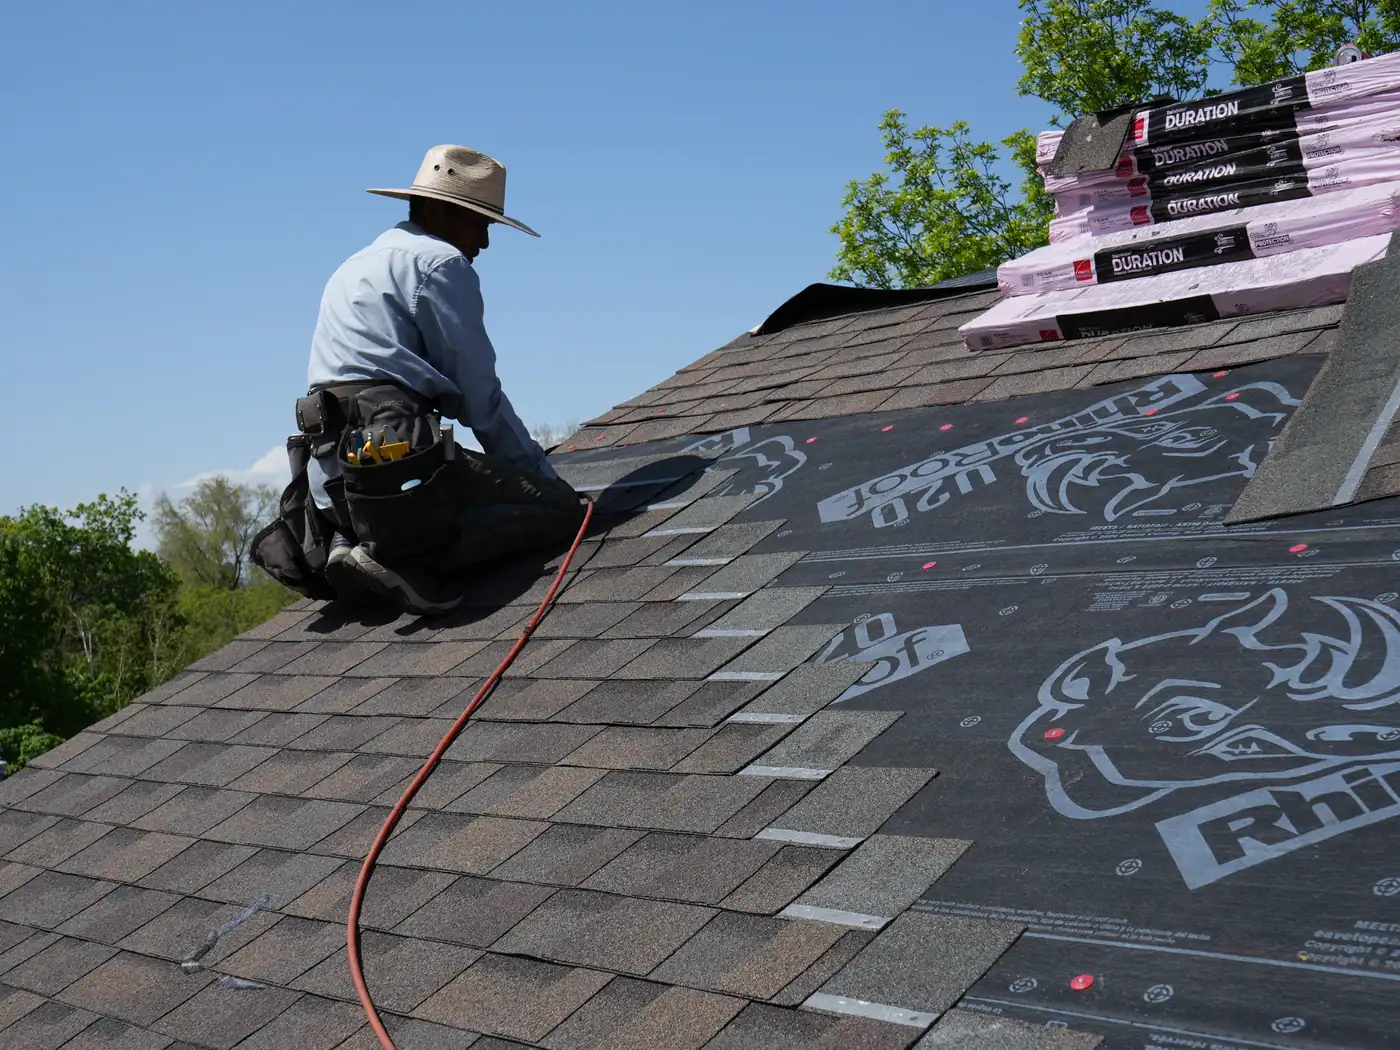
Step 05 of 06
Approved — we build
Materials ordered, a date set. Customers often tell us their tear-off and install took a day or two.
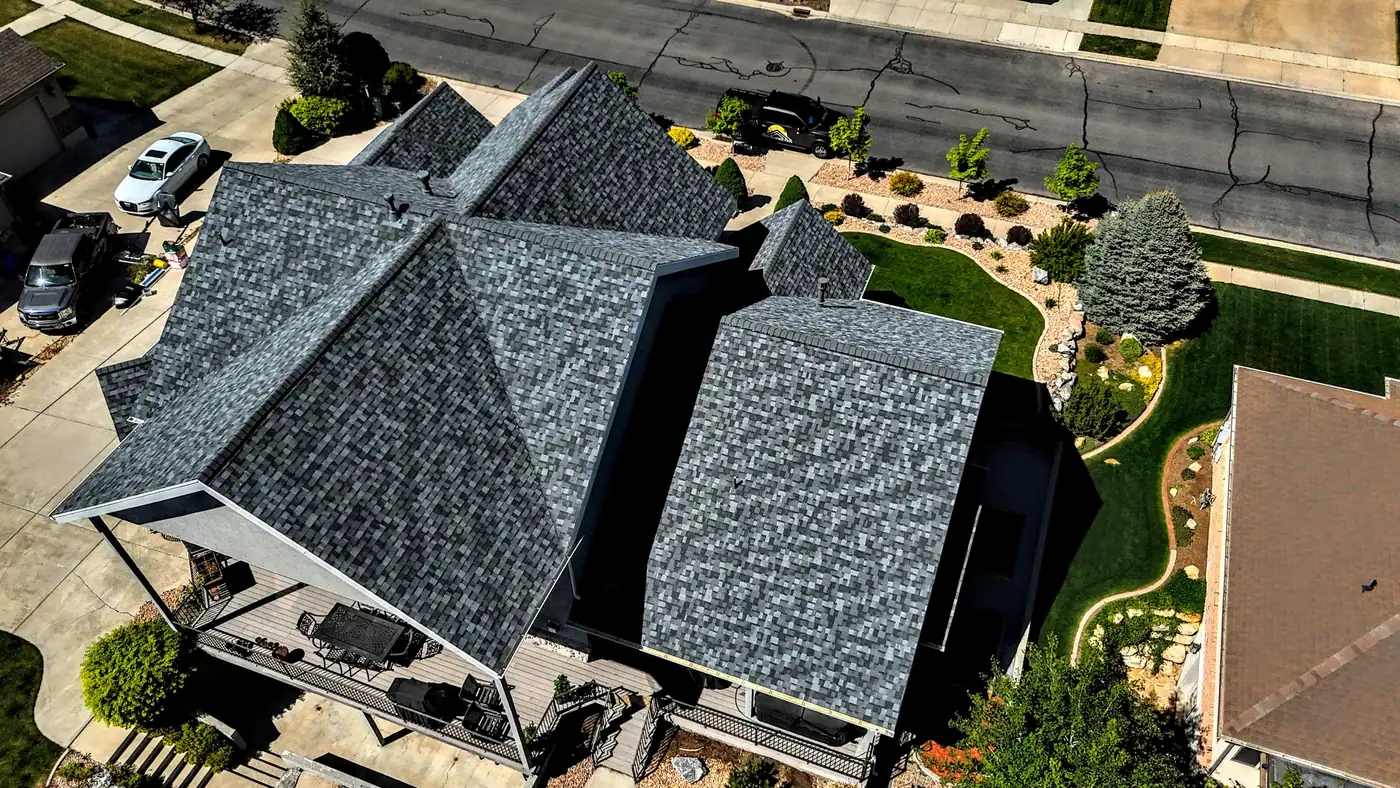
Step 06 of 06
Walkthrough & paperwork
Nails and debris cleaned up, final photos, and we finalize the paperwork with you.
Swipe through the six steps →
Step 01 of 06
Free inspection
We get on the roof — not just look from the driveway — and photograph every hit, lifted tab and cracked boot.
Usually covered
What insurance typically pays for.
Hail
Bruised or cracked shingles, granule loss, dented vents and gutters.
Wind
Lifted, creased, torn or missing shingles and ridge caps.
Falling trees & debris
Punctures, broken decking, damaged flashing.
Storm leaks
Water getting in through storm-damaged areas.
From customers who filed
It went like this.
5 out of 5 stars. Google review
“Thank you so much for our beautiful new roof! Phil was so good at keep us keeping us in the loop about the process, especially when working with our insurance to help cover the cost. When it came time to put on the new roof, it was just two days. They did an amazing job at keeping the mess of tear down out of the grass. The roof’s lines are as straight as an arrow and I love how the new roof vents blend in. They even painted my ABS plumbing vents to better match the new roof. 10 out of 10, would recommend!”
Dean Johnson 5 out of 5 stars. Google review
“John was extremely professional, to the point about bids and also helping with a wind damage claim. He called the insurance company directly and handled everything. His crew was punctual and cleaned up all the nails and roofing material. He checked several times after the completion to make sure everything was done correctly. Great experience.”
Calvin Nakamura
Questions
Insurance claim FAQ
- Is it really free to have you look?
- Yes. The inspection and the photo report cost nothing, and there's no obligation to hire us.
- What if it isn't storm damage?
- We'll tell you what we found and what we'd recommend — with no obligation. Whether to file is your call.
- Will you meet my insurance adjuster?
- Yes. We're on the roof when the adjuster inspects so the damage we documented is seen. The claim decision is between you and your insurer.
- What if my claim is denied?
- We'll go over the denial with you, explain what we found, and help you understand your options — including a repair-only scope or financing.
- Will filing raise my premium?
- Weather claims usually don't raise rates the way at-fault claims do, but every policy is different — ask your agent.
- Can financing cover my deductible?
- Often, yes. No payments and no interest for 12 months, on approved credit.
We're roofers, not public adjusters or attorneys: we document damage, provide estimates and meet your adjuster to show what we found. Policy questions go to your insurer or agent.
No pressure. No cost.
Think the storm got your roof?
We'll get on the roof, photograph what we find, and tell you plainly whether you need a repair, a replacement, or nothing at all.
(801) 688-3853Open 24 hours · or email john@utahroofingpros.com
Instant online estimateA ballpark price before anyone climbs a ladder — our estimator, powered by Roofr.
Request your inspection
Takes a minute. We'll call you back to set a time.